- Full-year RevPAR forecast raised to 1.5 to 2.5 percent.
- U.S. net rooms growth rate up for third consecutive quarter.
- Adjusted EBITDA guidance increases despite lower net income outlook.
CHOICE HOTELS INTERNATIONAL raised its full-year 2026 U.S. and global RevPAR forecasts after U.S. RevPAR increased 3.8 percent in the third quarter. The company’s U.S. net rooms growth rate also improved for the third consecutive quarter.
Global RevPAR increased 3.9 percent on a currency-neutral basis, while international RevPAR rose 3.7 percent, Choice said in a statement. The company’s global room count grew 1.7 percent year over year to 660,614 as of Sept. 30.
 Choice raised full-year RevPAR growth forecasts to 1.5 percent to 2.5 percent in the U.S. and globally. Pictured is Dom Dragisich, Choice president and CEO.Photo credit: Choice Hotels International
“Our third-quarter results reflect continued progress against our key priorities: the U.S. net rooms growth rate improved for the third consecutive quarter, U.S. RevPAR growth strengthened, and capital recycling is underway,” said Dom Dragisich, Choice president and CEO.
Choice now expects U.S. and global RevPAR growth of 1.5 percent to 2.5 percent for the full year, compared with previous forecasts of 0 percent to 1.25 percent in the U.S. and 0 percent to 1 percent globally, the statement said. U.S. RevPAR growth reflected a 1 percent increase in average daily rate and a 160-basis-point improvement in occupancy, with strength in the West South Central and Midwest regions.
Third-quarter revenue increased 2.5 percent to $458 million from $447 million a year earlier. Franchise and management fees rose 5 percent to $204 million, primarily reflecting higher U.S. royalties, franchisee programs and services revenue, and international royalties. The U.S. average royalty rate expanded 8 basis points to 5.23 percent.
Adjusted EBITDA increased 1 percent to $193 million or 5 percent excluding liquidated damages revenue of $3.3 million in the latest quarter and $9.5 million a year earlier. Adjusted diluted earnings per share rose 11 percent to $2.33 from $2.10, benefiting from higher franchise and management fees and share repurchases. Adjusted net income increased to $105 million from $98 million.
Reported net income declined 68 percent to $58 million, or $1.28 per diluted share, from $180 million, or $3.86 per diluted share, Choice said. The decline primarily reflected a $100 million gain from a joint venture acquisition recognized in the prior-year quarter. Current-quarter results included a $24 million charge related to terminating an arrangement involving an option to acquire a European hospitality business operating primarily under a lease-based model, and a $6 million non-cash impairment charge related to two owned hotels; both were excluded from adjusted results.
Rooms growth, development pipeline
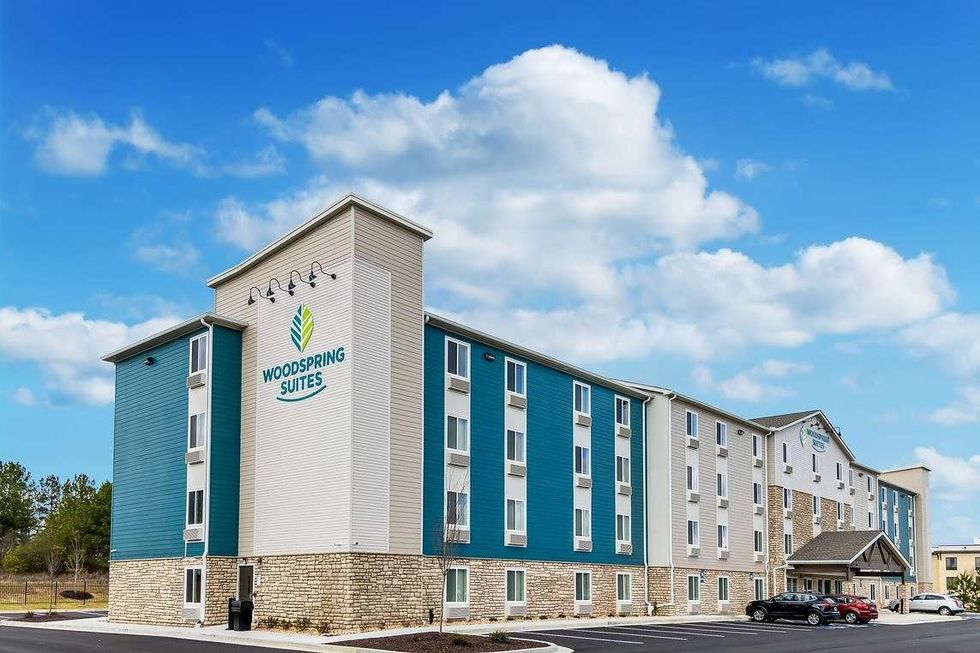 Extended-stay rooms grew 10.7 percent, marking 13 quarters of double-digit growth.Photo credit: Choice Hotels International
International rooms increased 7.3 percent to 162,399, while the U.S. portfolio remained approximately flat at 498,215 rooms. Global net rooms across the company’s upscale, extended-stay and midscale brands grew 2.5 percent, while extended-stay rooms increased 10.7 percent, marking the 13th consecutive quarter of double-digit growth. Choice also opened its 600th extended-stay hotel during the quarter.
U.S. franchise agreements awarded increased 24 percent year over year, representing 6,900 rooms for development, the company said. The U.S. conversion pipeline reached 25,500 rooms, up 6 percent from the previous quarter and 29 percent year over year. The global pipeline totaled 78,200 rooms, including 71,700 in the U.S.; extended-stay projects accounted for 30,300 rooms, or 39 percent of the total, while 96 percent was concentrated in extended-stay, midscale and upscale brands.
U.S. room openings totaled 4,400 in the quarter, compared with 4,800 a year earlier, although openings for the first nine months increased 17 percent. Third-quarter U.S. room exits declined 23 percent year over year. Global room openings totaled 6,000, compared with 12,800 a year earlier, which included a 7,400-room international portfolio conversion.
Dragisich said the company expects U.S. net rooms growth to accelerate to approximately 1 percent by year-end, supported by stronger demand trends.
Asset-light strategy fuels growth
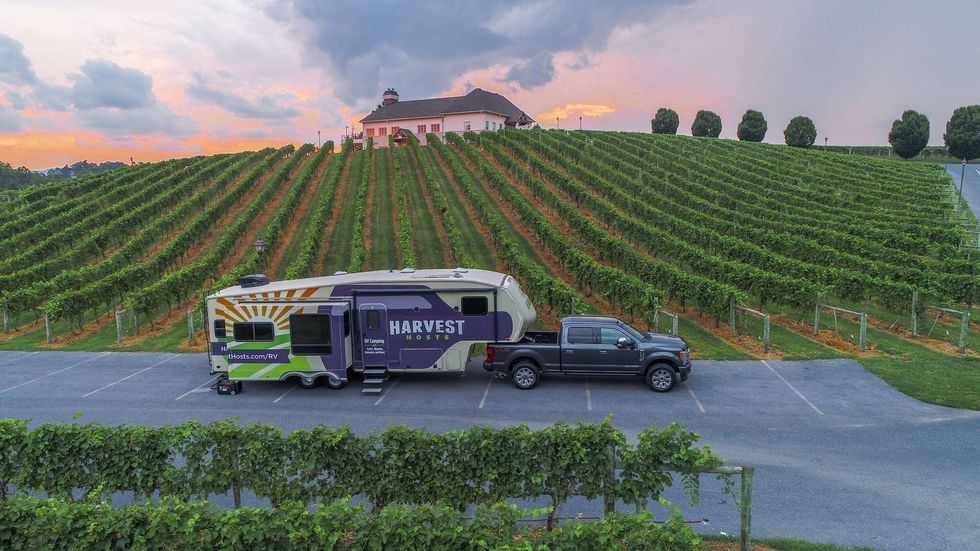 Choice acquired Harvest Hosts for $130 million, expanding into outdoor travel and recurring revenue.Photo credit: Choice Hotels International
Choice continued its asset-light strategy by selling two owned hotels after the quarter, generating estimated net cash proceeds of approximately $34 million while retaining franchise agreements for both properties.
As of Nov. 2, the company owned 17 operating hotels, with one additional property under construction, Choice said. Net capital outlays for hotel development and lending activities declined 56 percent to $36.3 million during the first nine months, while full-year hotel development-related outlays, net of proceeds from the two recent hotel sales, are expected to fall to approximately $20 million from $103.4 million in 2025, assuming no additional hotel sales.
On Oct. 1, Choice acquired Harvest Hosts, an asset-light RV travel subscription platform, for approximately $130 million, expanding its offerings into the outdoor travel market and adding a recurring-revenue business.
The company raised its full-year adjusted EBITDA guidance to $641 million to $651 million from $635 million to $650 million, citing stronger global RevPAR, higher U.S. royalty rates and an estimated $1 million net benefit from Harvest Hosts and the two hotel sales, partly offset by higher adjusted selling, general and administrative expenses.
Adjusted SG&A growth, excluding Harvest Hosts, is now expected to be approximately 9 percent, compared with the previous mid-single-digit forecast, primarily reflecting non-recurring spending on strategic initiatives and artificial intelligence-enabled capabilities, as well as higher accounts receivable reserves.
Choice lowered its full-year net income guidance to $178 million to $185 million from $230 million to $241 million, primarily reflecting higher expected reimbursable marketing and reservation system expenses, the contract termination charge, hotel impairments, lower expected equity earnings and higher interest expense, the statement said. Adjusted diluted EPS is now forecast at $6.92 to $7.07, compared with the previous range of $6.86 to $7.10.
Choice returned $211 million to shareholders through dividends and share repurchases during the first nine months of 2026. Available liquidity stood at $928 million at the end of the third quarter.