- U.S. RevPAR rises 6 percent year-over-year.
- Adjusted EPS outlook increases to $4.84–$4.92.
- Development pipeline reaches a record 264,000 rooms.
WYNDHAM HOTELS & RESORTS raised its full-year 2026 earnings outlook as U.S. RevPAR grew 6 percent in the third quarter. The U.S. gains balanced against international revenue declines.
The company reported its net revenues rose 7 percent to $410 million, while net income fell 6 percent to $99 million. It reported global RevPAR growth of 2 percent in constant currency for the quarter ended Sept. 30. Diluted earnings per share fell to $1.33 from $1.36.
“Our third quarter results demonstrate our team’s continued execution and the strength of Wyndham’s asset-light, highly cash-generative business model,” said Geoff Ballotti, Wyndham president and chief executive officer. “We delivered broad-based U.S. RevPAR growth outperforming our initial expectations, as well as market share gains.”
Wyndham now expects adjusted diluted EPS of $4.84 to $4.92, up from its previous forecast of $4.71 to $4.83, the company said. Adjusted net income is projected at $363 million to $369 million, compared with the previous range of $355 million to $365 million.
The company raised the lower end of its adjusted EBITDA forecast to $740 million from $735 million, keeping the upper end at $745 million. It expects global RevPAR growth of 0.5 percent to 1 percent in constant currency, compared with its previous forecast of 0 percent to 1 percent.
Wyndham lowered its room growth outlook to approximately 4 percent from 4 percent to 4.5 percent. It expects net revenues of $1.48 billion to $1.495 billion and a free cash flow conversion rate of 55 percent to 60 percent.
U.S. gains offset international decline
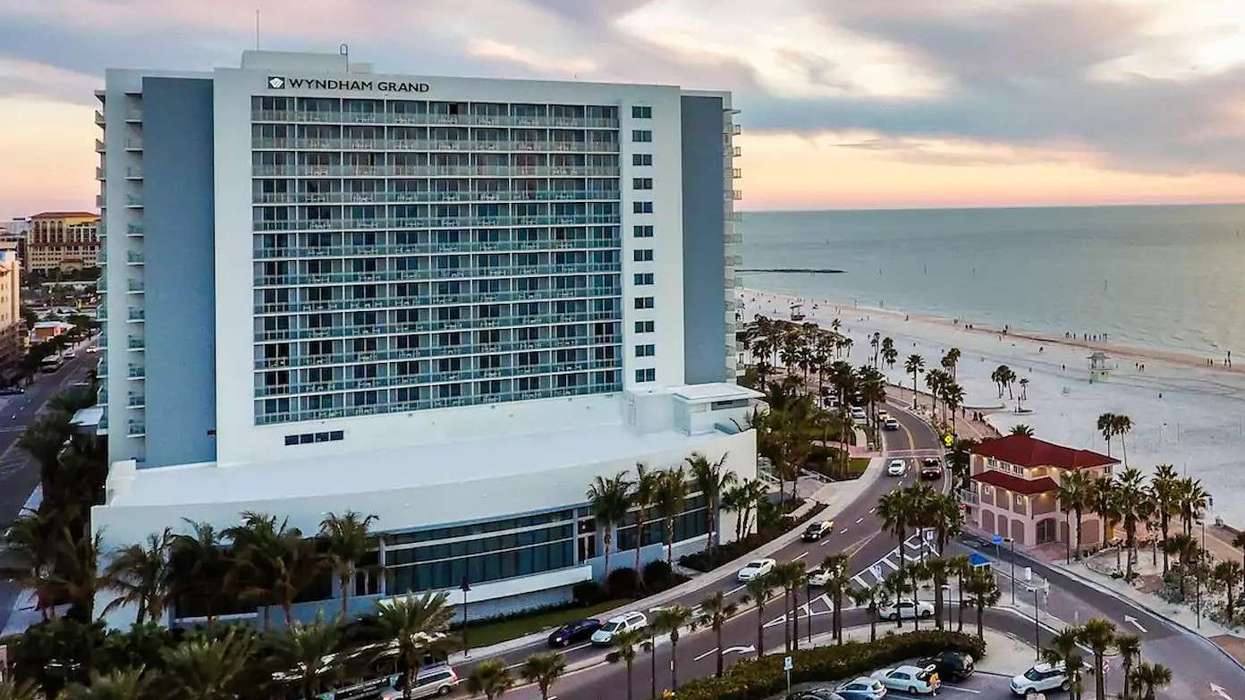
 U.S. RevPAR rose 6 percent to $58.35, driven by higher occupancy and rates.Photo credit: Wyndham Hotels & Resorts
U.S. RevPAR reached $58.35, up 6 percent year-over-year and up from about 2 percent growth in the second quarter, Wyndham said. The company attributed the increase to higher occupancy and average daily rates, with gains across nearly all regions, including the Midwest, Texas, Florida and California.
International RevPAR declined 3 percent in constant currency to $41.79, though the decline narrowed from the second quarter. Canada grew 7 percent, while the rest of Asia Pacific increased 5 percent. Latin America and Europe, the Middle East and Africa each grew 2 percent. Greater China declined 10 percent as travel demand weakened, particularly in Tier 2 cities.
Wyndham’s global system totaled 877,400 rooms at Sept. 30, up 3 percent year-over-year. Excluding rooms associated with insolvent Revo Hospitality Group, rooms increased 4 percent to 864,400. The U.S. system declined 1 percent to 500,000 rooms, although midscale and above properties grew 2 percent. International rooms rose 7 percent to 377,400, or 11 percent excluding Revo.
The development pipeline grew 4 percent, excluding Revo, to a record 264,000 rooms across more than 2,200 hotels. About 69 percent of the pipeline is in midscale and above segments, and 17 percent is in extended stay. Approximately 78 percent involves new construction and 35 percent of those projects have broken ground.
The pipeline carries a premium of about 30 percent in royalties per room over existing domestic and international systems.
Wyndham delivered solid second-quarter results, with stronger-than-expected U.S. performance and a record global development pipeline. International markets, however, continued to lag.
Marketing fund timing weighs on earnings
 Wyndham expanded its share repurchase authorization by $400 million, with leverage at 3.6 times.Photo credit: Wyndham Hotels & Resorts Saint John/LinkedIn
Adjusted EBITDA declined 3 percent to $207 million from $213 million a year earlier. Adjusted diluted EPS fell to $1.43 from $1.46. Royalties and franchise fees rose 6 percent to $156 million.
Marketing fund revenues exceeded expenses by $1 million, compared with $18 million in the prior-year quarter. On a comparable basis that neutralizes this variability, adjusted EBITDA rose 5 percent and adjusted diluted EPS increased about 9 percent.
Net cash provided by operating activities was $93 million. Free cash flow totaled $100 million, reflecting operating cash flow adjusted for capital expenditures and net payments of development advance notes. Wyndham returned $123 million to shareholders through $91 million in share repurchases and $32 million in dividends.
The board approved a $400 million increase in the share repurchase authorization. Wyndham ended the quarter with $71 million in cash and $988 million in total liquidity. Net debt was $2.66 billion, and its net debt leverage ratio stood at 3.6 times, within its target range of three to four times.
Separately, Wyndham will help developers build Sports Illustrated Resorts as standalone hotels or mixed-use projects combining lodging, vacation ownership and residences.